Insurance or invest first? That RM500 plan from Mum is the problem.
MoneyMama · 8 September 2026 · 6 min read
Your mum says it is time to pay for your own insurance. She has never once said it is time to invest.
And the voice in your head says the opposite. I am 24 and healthy. Why pay RM300 for something I will not claim for years? Put it in a fund lah. Sit down first. You are both arguing about the wrong thing.
Here is the short answer. Insurance and investing are not a queue. You run both from your first salary. Sort out cover first. Start with a medical card. Then critical illness. Then life cover. Keep those premiums at 5% to 10% of your pay. That is RM150 to RM300 on RM3,000. Then move 20% out on payday to save and invest. But before you buy anything, read the plan your parents already pay for. That is usually where the problem sits.
A surgeon will not wait while you save up
A fever at the clinic costs RM100. You pay it from your pocket. A bad accident with surgery can cost RM50,000 or RM60,000. You cannot ask the doctor to wait eight months. And while you heal, you are not earning.
That is the whole reason protection comes first. You can plan a house years ahead. You cannot plan the day you get sick.
But “sort it out” does not mean “go and buy”. If Mama tells you to eat, you check the fridge before you tapau. Same with insurance. Check what you already have.
Mum’s old plan might be eating your pay
Many fresh grads already have a plan. In your first year of work, a parent hands it over. You can take over the payments now. Most people just pay. Ask them what it covers and they cannot say.
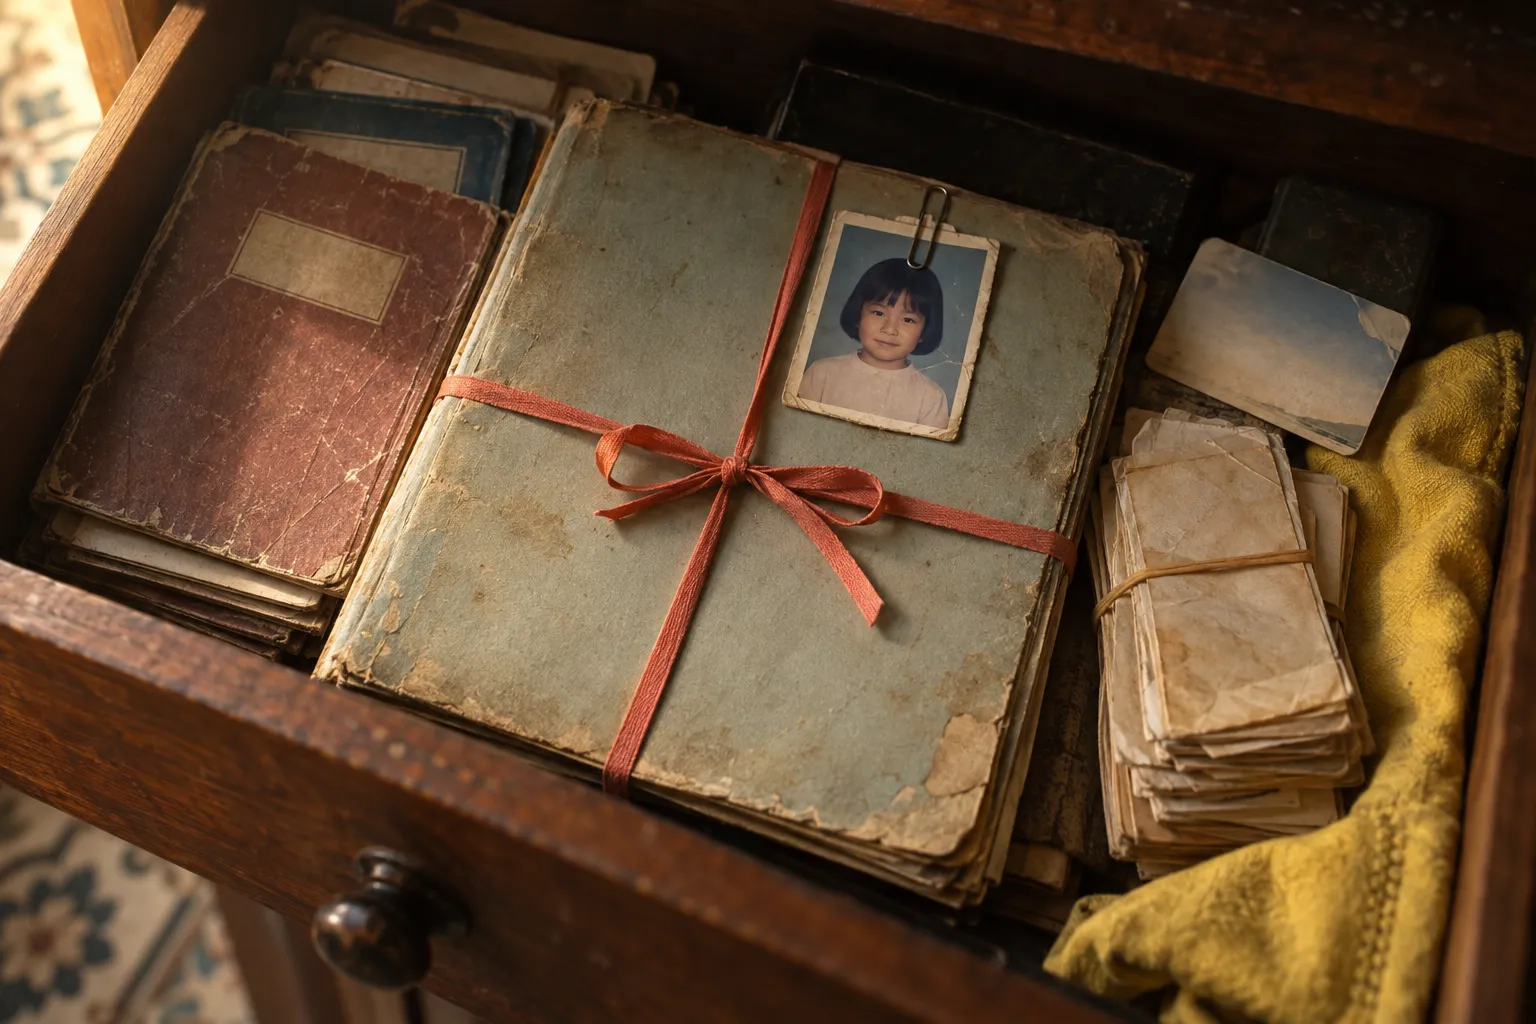
Now Mama has to be honest with you. Your parents chose that plan on their budget, not yours. RM300 a month was fine for a home with two incomes. Some old plans cost RM500. On a RM3,000 salary, that is close to 17% of your pay. Something else must give. Usually it is your savings.
So “insurance or invest?” is often just a budget fight. Reading the policy fixes most of it. Check four things:
- Is there a medical card? Look at the yearly limit and any deductible, the part you pay first.
- Is there critical illness cover? It should be a cash lump sum. Compare it to three years of your pay.
- How much goes into savings? If most of it buys units, the cover was an afterthought.
- What is the total? Above 10% of your income, ask your agent for the same cover at a lower price.
Medical card first. Critical illness next. Life cover last.
People say “I have insurance already” like it is one thing. It is at least two, and they do different jobs.
A medical card pays the hospital. Think of a credit card that only works at one shop. You never see the cash. You will use it more than you think. On the show, a harmless growth from sport cost RM9,000 to remove. Without a card, that is a year of saving gone.
Critical illness cover pays you. You get a cash lump sum when you are diagnosed. You spend it on anything. Rent, food, the salary you lost.
Life cover pays your family when you die. At 25 with no spouse, kids or house loan, nobody depends on your income. The one real cost left is your funeral, about RM50,000. So a small policy is enough, and it comes last.
Cancer is mostly not a hospital bill
This one Mama really must press. The big cost of a serious illness is the life around it.
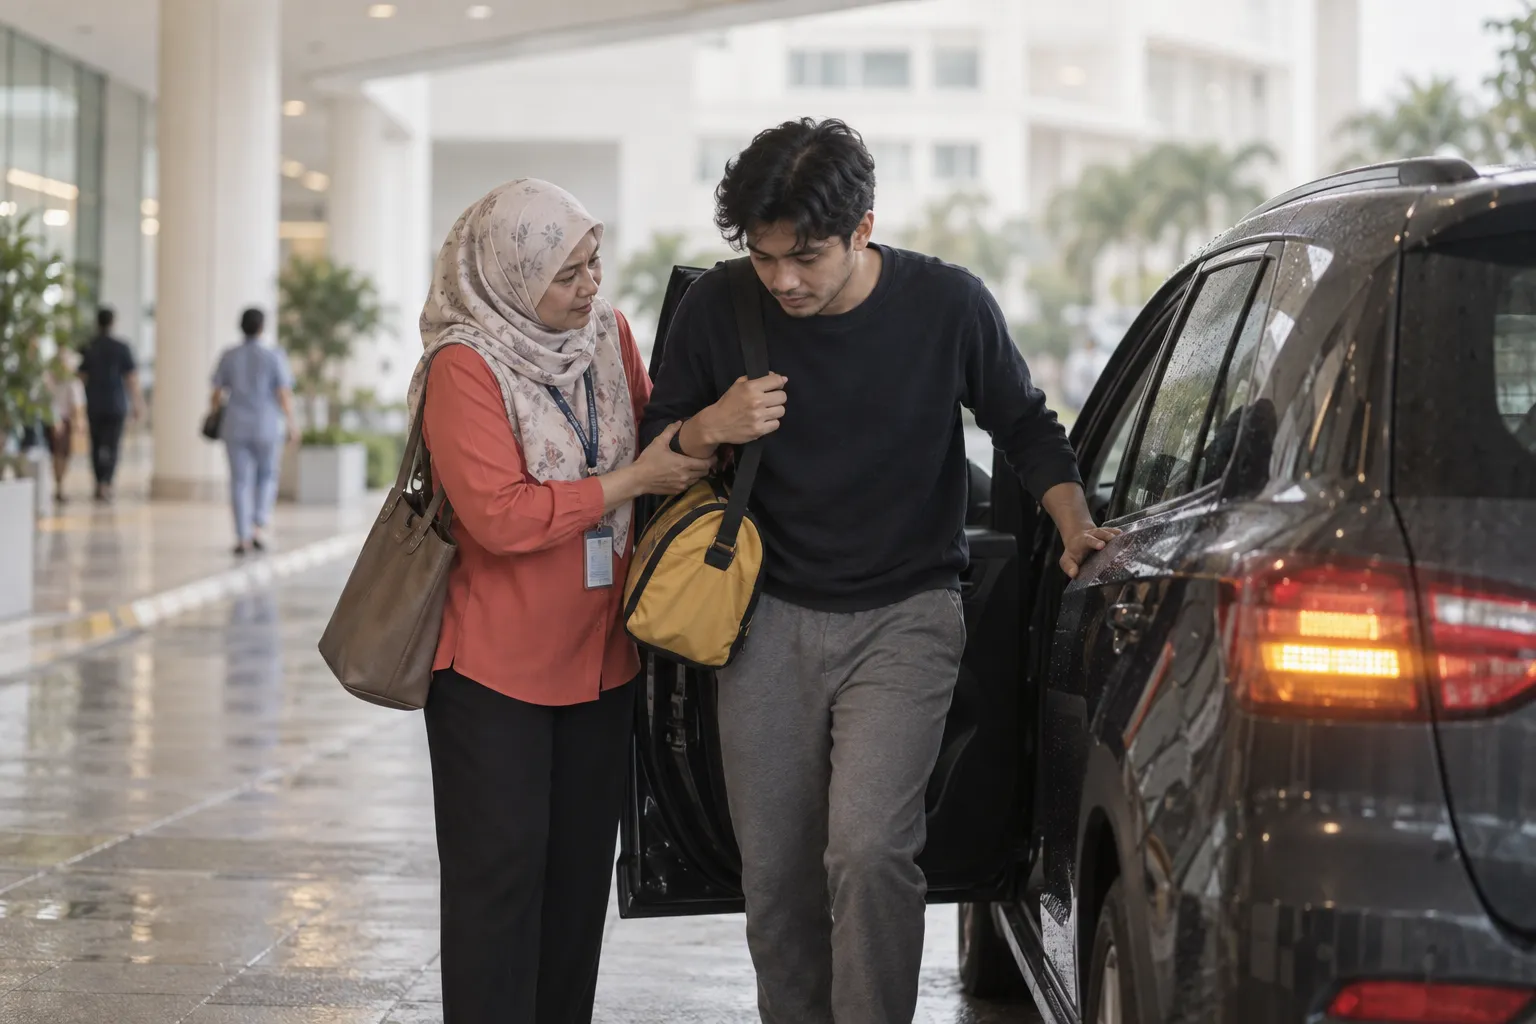
Say you need treatment three times a week. You rent a small place near the hospital, RM1,500 a month. The mamak budget goes, because the doctor wants you to eat well. A parent cuts work to drive you. That adds up to RM5,000 or RM6,000 more a month. Treatment can run two or three years. Then add the pay you stop earning. RM3,000 for two years is RM72,000. The total can pass RM200,000.
None of that is on a hospital bill. That is why the rule is three years of income. On RM3,000 a month, that is about RM108,000. If that costs too much, take one year. One year beats nothing.
The “invest” part of your plan grows like an FD
Agents know fresh grads want to invest. So the pitch comes as two in one. It protects you and grows your money.
Mama likes nasi campur. Rice is the base, then you add dishes. An investment-linked plan works the same way. Your premium buys units. Each month some units are sold to pay for the cover you added. It is flexible. In Malaysia, it is often the easiest way to hold a medical card.
As a place to grow money, though, it is weak. These plans usually grow at about 2% to 4% a year. That is fixed deposit level. So use the plan for cover. Do your investing somewhere cheaper.
What Mama wants you to do this month
- Ask your parents for every policy file. Read it before you buy anything new.
- Sort cover in order. Medical card first. Then critical illness. Then a small life plan.
- Size critical illness at three years of pay. About RM108,000 on RM3,000.
- Cap premiums at 10% of pay. Ask your agent for the same cover at a lower price.
- Move 20% out on payday. Build three months of emergency fund first. Then split it, 10% saving and 10% investing.
That is RM300 for cover, RM300 for savings, RM300 for investing, and RM2,100 to live on. If your take-home is closer to RM2,500, use that number instead. Here is how to split your first salary. And expect medical premiums to rise over time. Mama explains why your medical card keeps costing more.
You do not have to choose
A fresh grad on RM3,000 can carry both. It only feels too hard when an old plan eats your pay. Nobody read it. And it was priced for your parents, not you. Read it, fix it, and the rest fits.
Mama can help you see the real numbers. Get the MoneyMama app. Type “insurance RM300” in the chat and Mama logs it. In a few months you will know exactly what your cover costs, and how much is left to grow.