Your first pay is RM2,500. Here is where each ringgit should go.
MoneyMama · 21 August 2026 · 6 min read
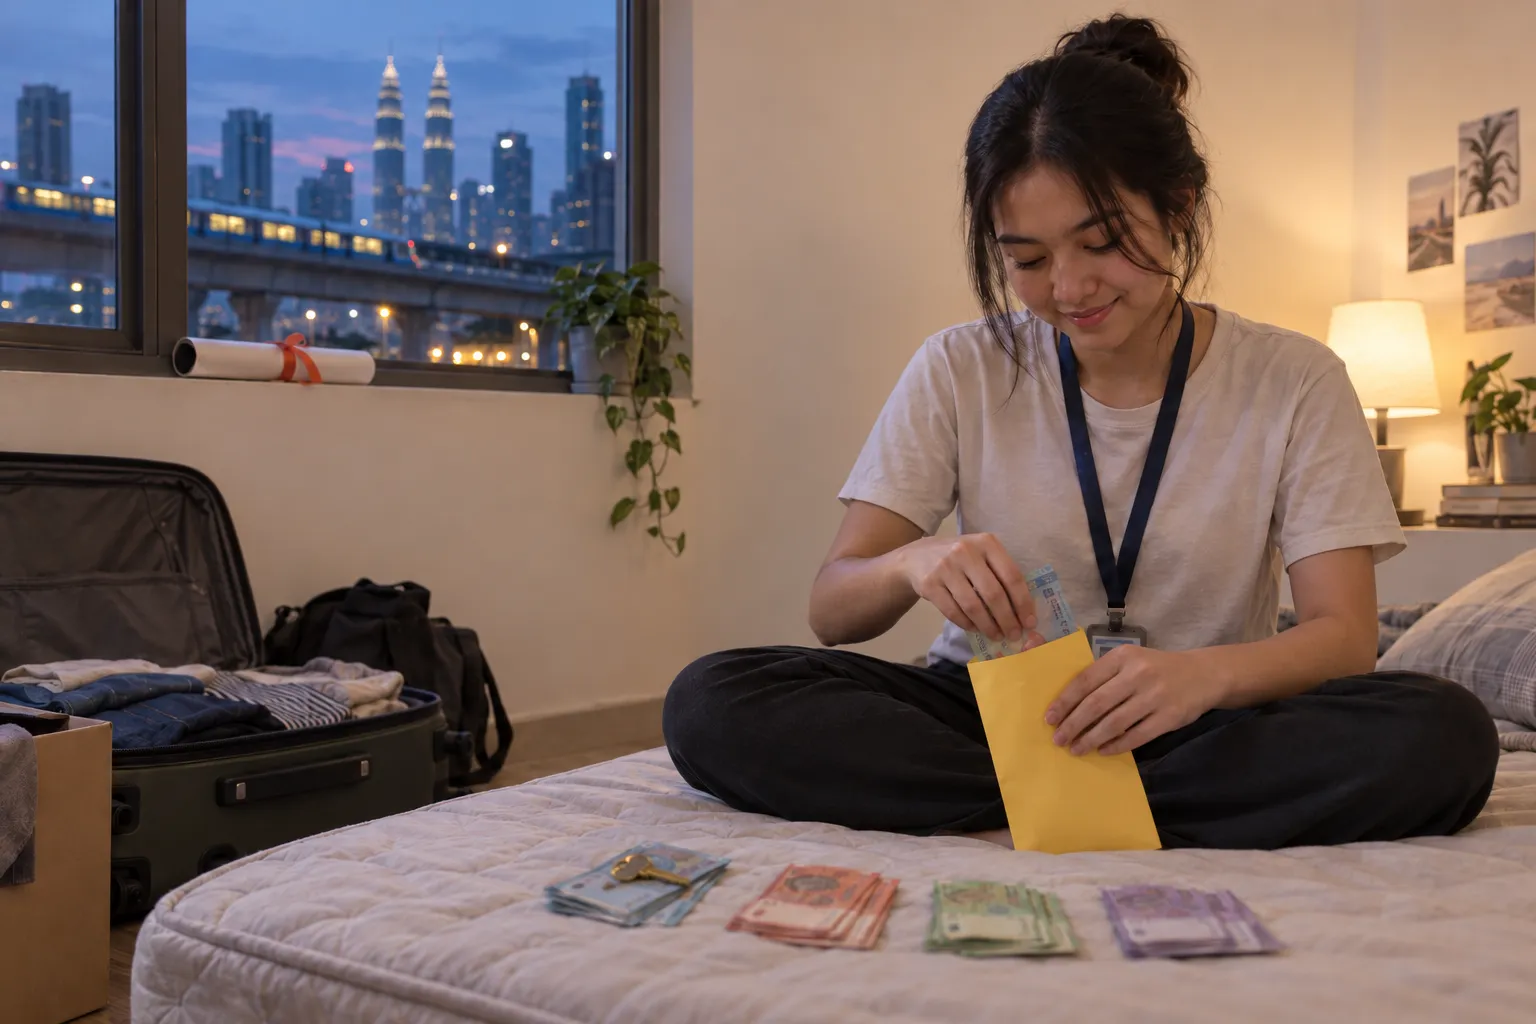
Aiyo, your first payslip. The offer letter said RM3,000. The bank says about RM2,500.
Mama knows what you thought. Where did RM500 go? I have not even spent anything yet. Sit down first. That money is not lost. And what you do with the RM2,500 in the next few months will set your habits for years.
Here is the short answer. Always budget from your take-home pay, not the offer letter. If you live with your parents, split it 50/30/20. That is RM1,250 for needs, RM750 for wants and RM500 for savings. If you rent in KL, use 40/30/20/10. That gives RM1,000 for needs, RM750 for rent, RM500 for savings and RM250 for wants. Either way, the savings leave your account first, on payday. Then you live on what is left.
Your RM500 did not disappear. It went to future you.
On RM3,000, 11% goes to your EPF. That is RM330. Your boss adds another 13% on top. SOCSO, EIS and maybe some tax take a little more. So what lands is about RM2,500.
Here is the good part. About a quarter of your pay is already saved for old age. You did nothing, and it is done. But you cannot touch EPF until you are old. So it will not help when your laptop breaks next year. That is why you still need to save from your take-home.
Living at home? Use 50/30/20.
If you live with your parents, lucky you. This split is easy to keep. On RM2,500:
- 50% for needs, RM1,250. Food, transport, a basic phone plan. The things you cannot skip.
- 30% for wants, RM750. The new phone, the trip with friends, the omakase dinner.
- 20% for savings, RM500. Build a cash buffer first. Invest later.
Nasi campur is a need. Omakase is a want. Both fill your stomach. Only one of them has to happen.
Now the part that stings: money for your parents
Mama has to be honest with you. The money you give your parents might be a want.
Ask one question. Can they manage without it? If your mum still works and you give because you love her, that is beautiful. It still goes in the wants box. If your family truly needs it to pay the bills, then it is a need. Then you spend less somewhere else. Either way, the money has to come from somewhere. So give it a box.
Save first, or you will save nothing
This one Mama really must press. If you spend first and save what is left, nothing is left. Every time.
Peter makes a good point on Mr Money TV. Lots of us end up old with just two things. Our EPF and our house. Why? Because we could not touch either one. The money we can reach, we spend. The money we lock away, we keep.
So on payday, move your RM500 out straight away. Put it in a separate account with no debit card. Then live on the rest. You will be surprised how well you make do.
Renting in KL? Your rent needs its own box.
If you came from outstation, the 50/30/20 split breaks. One room can eat half your needs money. So rent gets its own line.
That is RM1,000 for needs, RM750 for rent, RM500 for savings and only RM250 for wants. Yes, the fun money shrinks. Rent took it.
Rooms swing a lot. Li Xin’s friend pays about RM800 in Kepong. Li Xin once paid RM100 in Serdang. It was a storeroom with no aircon. She had to fold her bed to open the door. A room near the train costs more. A room far away costs less, but then you pay for Grab home at night. Nothing is free.
Rent went over? Take from both sides.
Say your room is RM1,000, not RM750. Where does the extra RM250 come from?
Take it from wants first. If wants alone cannot cover it, take half from wants and half from savings. Do not wipe one out fully.
Why? Because we all need a little fun. Take it all away and you blow up later. It is like the snacks at the counter. You already spent RM80, so what is RM2.50 more? Break a budget once and your brain says since I broke it already, spend lah. A budget you can keep beats a perfect one you drop by the 10th. Here is a simple payday routine that helps it stick.
Five train stations can save you a car loan
Three things make or break your budget. Where you work, where you stay, and how you get there.
Live one hour from work by train and it wears you down. Soon you want a car. Mama sees it all the time. A new Axia or Myvi costs RM600 to RM700 a month. Add petrol, parking and insurance and it is about RM1,000.
Now do the maths on RM2,500. Rent RM750. Car RM1,000. You have RM750 left for food, phone and everything else. Savings? Gone. As Peter says, either you eat or your car eats you.
Try to stay within five stations of work. The My50 pass gives you unlimited Rapid KL rides for RM50 a month. If you must have a car, keep the loan near 10% of your pay. That is RM300 on RM3,000. More on that in the real cost of owning a car.
Stay a student a little longer
In uni you lived on very little. Then the first salary lands, and suddenly the kopi must be the RM15 one.
Mama is not asking you to live in a storeroom. Just do not let your lifestyle grow as fast as your pay. Keep your student habits until you earn about RM5,000. Then the raise goes to savings, not a nicer room.
Your savings rate should grow too. 20% now, then 30%, then 50% or more. At home with no one to support, that jump can come at RM4,000 to RM5,000. Renting with no car, around RM5,000. With a car loan, closer to RM7,000.
What Mama wants you to do this payday
- Know your real number. Check your take-home, not the offer letter.
- Move 20% out on payday. Into an account with no debit card. Start your emergency fund there.
- Pick your split. 50/30/20 at home. 40/30/20/10 if you rent.
- Give parents’ money a box. Want or need, be honest.
- Keep some fun money, guilt-free. It stops you from giving up on the whole budget.
- Choose where you live with the job in mind. Five stations, if you can.
Small start, big habit
If you cannot do all of this next month, that is okay. Cut a little each month. Save RM200 this month, RM300 the next. You are building a habit, not passing a test.
Mama can help you see where the RM2,500 really goes. Get the MoneyMama app. Type “lunch RM12” in the chat and Mama sorts it out. By month three, you will know your real numbers better than your boss knows your payslip.